By Jennet Parkar October 4, 2026
An MCA early payoff discount is not automatic. Paying an advance sooner can reduce the amount due when the executed agreement or MCA prepayment addendum provides a lower early-payoff amount, or when the funder separately agrees to a discounted payoff. Before sending money, obtain a written merchant cash advance payoff quote showing the amount and satisfaction terms.
MCA Early Payoff Discount: The Short Answer
An MCA early payoff discount exists only when the governing documents or a later written agreement actually reduce what the merchant must deliver to satisfy the transaction. The ability to prepay and the right to receive a discount are two different things.
That distinction is visible in current publicly filed contracts. A June 30, 2026 Standard Merchant Cash Advance Agreement filed with the SEC gave the merchant the right to prepay without a prepayment penalty, but stated that termination required payment of the then-remaining balance of the Receivables Purchased Amount. In other words, early payment was allowed, but the cited provision did not itself create a discount.
A September 2025 SEC-filed agreement demonstrates the opposite structure. It listed a $5 million Purchase Price, a $6.3 million standard Receivables Purchased Amount, a $5,086,665 Receivables Purchased Amount if paid in full within 30 days, and a $5,226,665 amount if paid within 60 days. Those are actual contract-specific reductions, not assumptions about how all MCAs operate.
| Situation | Does Paying Early Automatically Save Money? | What Controls the Result? |
| Agreement expressly provides an early-payoff reduction | Potentially | Contract or addendum |
| Agreement permits prepayment but gives no discount | Usually not from timing alone | Remaining Purchased Amount and other payoff terms |
| Funder agrees to a negotiated discount | Potentially | Written negotiated payoff |
| Merchant enters a renewal | Different transaction | Renewal terms, old payoff and net new funding |
| Portal shows an estimated balance | Not necessarily | Written payoff quote and contract |
A current contract example shows why that distinction matters. A June 2026 SEC-filed merchant cash advance agreement permitted the merchant to make prepayments without a penalty, but its prepayment provision still required the balance of the Receivables Purchased Amount to terminate the agreement. In that contract, paying early was permitted; the cited clause did not automatically reduce the purchased amount.
A genuine MCA early payoff discount should therefore be proved by the documents, not inferred from the fact that a merchant has cash available.
California law reinforces the importance of understanding these terms before closing. For covered commercial-financing offers, current California Financial Code §22802 requires disclosure of several items, including a description of prepayment policies.
New York takes a similar disclosure-focused approach. For covered sales-based financing, Financial Services Law §803 requires disclosure of whether an early payoff or refinance would require unpaid finance charges and whether additional fees would apply.
Neither law means every MCA must offer an early-payment discount.
Why Paying an MCA Early Does Not Necessarily Reduce Its Cost
An MCA or sales-based-financing agreement commonly identifies a Purchase Price and a larger Purchased Amount or Receivables Purchased Amount.
For illustration:
Purchase Price: $100,000
Illustrative factor: 1.40
Purchased Amount: $140,000
That $140,000 figure should not automatically be treated like the outstanding principal on an amortizing term loan.
With a conventional amortizing loan, interest typically develops over time on the unpaid principal according to the loan documents. Paying principal earlier can therefore reduce future interest in many loan structures.
A fixed Purchased Amount works differently. If the executed MCA documents say the merchant sold $140,000 of receivables for a $100,000 Purchase Price, merely delivering those receivables faster does not necessarily change the contractual Purchased Amount.
This is what merchants often mean when they say the factor rate does not amortize. More precisely, where the agreement establishes a fixed Purchased Amount, the factor-based cost does not automatically decline over time in the way interest on an amortizing balance may decline.
The June 2026 SEC-filed Avanza agreement is a useful current example. It listed a $1 million Purchase Price and a $1,499,900 Receivables Purchased Amount, while its prepayment clause allowed termination by paying the remaining balance of that Purchased Amount.
So the statement factor rate does not amortize should be understood as a description of that type of contractual economics—not as a universal legal characterization of every product marketed as an MCA.
The exact agreement still controls.
Current Contract Evidence: Early Payment Can Mean Very Different Things
The best way to understand an MCA early payoff discount is to compare actual agreements.
Example 1: 2026 agreement — prepayment allowed, but no stated payoff reduction
The June 30, 2026 Avanza agreement stated:
- Purchase Price: $1,000,000
- Receivables Purchased Amount: $1,499,900
- merchant could make prepayments without a penalty; and
- termination could be achieved by paying the balance of the Receivables Purchased Amount.
That provision proves an important distinction: “no prepayment penalty” is not the same thing as “prepayment discount.”
A merchant reading only “no penalty” might assume early payment creates savings. The remaining language shows why the complete clause matters.
Example 2: 2025 agreement — lower Purchased Amount for timely payoff
The September 2025 Cedar Advance agreement used an expressly different model.
It listed:
- standard Purchase Price: $5,000,000;
- standard Receivables Purchased Amount: $6,300,000;
- 30-day Purchased Amount: $5,086,665; and
- 60-day Purchased Amount: $5,226,665.
The agreement then stated that if the merchant paid in full within the applicable 30- or 60-day window, the corresponding lower Receivables Purchased Amount would apply.
That is a real merchant cash advance prepayment discount documented in an actual SEC-filed agreement.
It is also proof that merchants should not assume a universal 30/60/90 schedule. One agreement may use 30 and 60 days. Another may use different dates, fixed dollar amounts, reduced factors, or no discount at all.
What an Early Payoff or MCA Prepayment Addendum Actually Does
An early payoff addendum MCA provision changes the economics only to the extent its language actually modifies the amount otherwise payable.
A proper MCA prepayment addendum may specify:
- a lower Purchased Amount;
- a reduced factor rate early payoff calculation;
- one or more eligibility windows;
- a deadline for receipt of funds;
- whether existing remittances receive credit;
- whether the merchant must remain current;
- whether a default eliminates discount eligibility;
- how outstanding fees are handled;
- whether notice is required;
- how pending ACH or split payments are treated; and
- what constitutes final satisfaction.
The contractual detail matters because two agreements can both advertise early payment while producing completely different results.
For example, one merchant cash advance prepayment discount could reset the Purchased Amount from $140,000 to $120,000 if paid during an early window. Another agreement could simply permit the merchant to accelerate the remaining $140,000 Purchased Amount without reducing it.
Where commercial-financing disclosure laws apply, the offer documents may also help identify whether early payment changes the economics.
For example, New York Financial Services Law §803 requires covered sales-based financing disclosures to address whether an early payoff or refinance would require payment of specified remaining finance charges and whether additional prepayment fees would apply. The disclosure requirement does not itself guarantee an early-payoff discount.
How Merchant Cash Advance Prepayment Discount Tiers Work
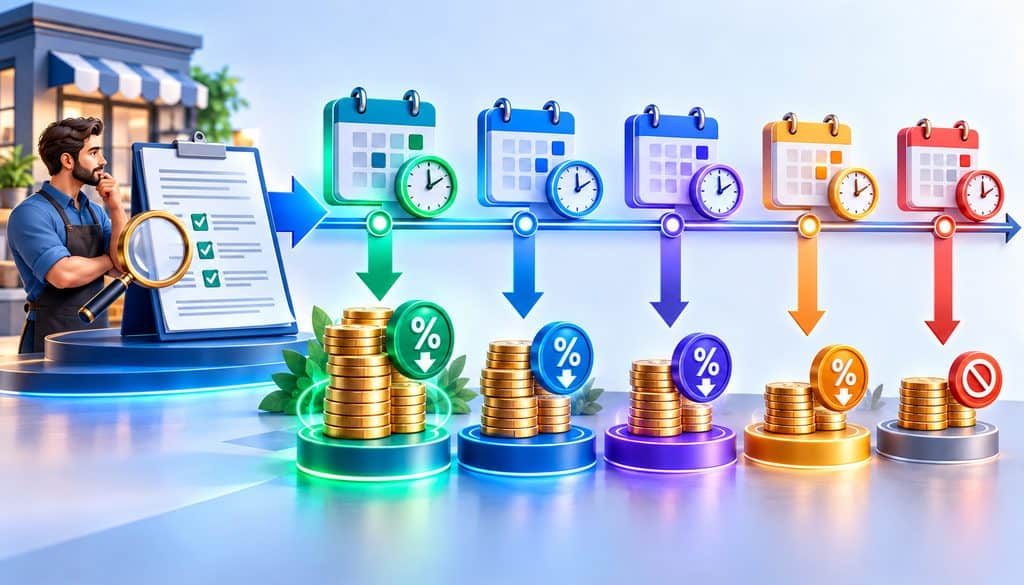
Prepayment discount tiers are not standardized.
A hypothetical agreement could use:
- first eligibility window: effective factor of 1.20;
- second window: effective factor of 1.25;
- third window: effective factor of 1.30;
- after the final window: original 1.40 Purchased Amount.
Illustrative example only — actual MCA prepayment discount tiers vary by contract.
A funder could instead state fixed dollar payoff amounts, as the 2025 Cedar agreement did.
That is why questions about prepayment discount tiers in merchant cash advance contracts should always begin with the executed agreement rather than a generic industry schedule.
Worked Example: How an MCA Early Payoff Discount Changes the Numbers
To see how an MCA early payoff discount affects actual cash owed, assume the following hypothetical transaction:
- Purchase Price: $100,000
- original factor: 1.40
- original Purchased Amount: $140,000
- remittances already received: $20,000
Scenario A — Full Contractual Purchased Amount
Without any payoff reduction:
Original Purchased Amount: $140,000
Remitted already: $20,000
Cash still owed: $120,000
The merchant ultimately delivers $140,000 in total.
Scenario B — Early Payoff With a Discount Addendum
Assume a hypothetical MCA prepayment addendum changes the total Purchased Amount according to the payment date.
| Structure | Applicable Purchased Amount | Already Remitted | Payoff Still Due | Savings vs. Original $140,000 |
| Early tier — 1.20 | $120,000 | $20,000 | $100,000 | $20,000 |
| Second tier — 1.25 | $125,000 | $20,000 | $105,000 | $15,000 |
| Third tier — 1.30 | $130,000 | $20,000 | $110,000 | $10,000 |
| Original 1.40 amount | $140,000 | $20,000 | $120,000 | $0 |
The $20,000 already remitted is not paid twice. It is credited in the calculation.
The reduced factor rate early payoff is what creates the savings in this hypothetical—not simply paying on an earlier calendar date.
Scenario C — Early Payment With No Discount
Assume the merchant still has $120,000 remaining under the $140,000 Purchased Amount and the agreement contains no reduction.
The merchant may be able to send the entire $120,000 today and close the transaction. But if the documents do not reduce the Purchased Amount, the pay off MCA early savings attributable specifically to a discount are $0.
The merchant has accelerated satisfaction, not necessarily reduced contractual cost.
How to Calculate a Reduced MCA Payoff
Where the agreement uses a reduced factor, a useful working formula is:
Discounted Purchased Amount = Original Purchase Price × Discounted Factor
Then:
Payoff Due = Discounted Purchased Amount − Eligible Remittances Already Credited
Example:
$100,000 × 1.25 = $125,000 discounted Purchased Amount
If $20,000 has already been credited:
$125,000 − $20,000 = $105,000 payoff
This is only a working formula. The actual merchant cash advance payoff quote should control because a contract may use fixed dollar payoff amounts, additional charges, different crediting rules or pending transactions.
Before accepting a payoff figure, reconcile the remittances already collected against bank statements, processor records, and the funder’s payment history.
If the agreement allows adjustments based on actual revenue, the reconciliation provision in a revenue-based financing agreement can determine how overcollections, undercollections, or payment true-ups should be handled before the final payoff is calculated.
What If There Is No MCA Early Payoff Discount in the Contract?
If there is no contractual MCA early payoff discount, the merchant can still ask whether the funder will accept a lower lump-sum payoff.
But it should be treated as a negotiation, not a contractual entitlement.
A funder may have commercial reasons to consider a discounted MCA payoff. Depending on the facts, immediate payment can eliminate future collection uncertainty, reduce servicing work, facilitate a refinance or business sale, or resolve a strained funding relationship.
The funder can also simply decline.
A merchant should therefore avoid wording such as, “I am entitled to a discount because I am paying early,” unless the contract actually creates that right.
A better approach is: “What amount would you accept on October 5, 2026 as full satisfaction of the agreement?”
That invites a merchant cash advance lump-sum payoff discussion without misstating the merchant’s contractual rights.
How to Ask for a Discounted MCA Payoff
Even without a contractual MCA early payoff discount, a merchant can make a structured request.
- Collect the executed agreement and every addendum.
- Identify the Purchase Price and Purchased Amount.
- Locate all prepayment, early-payment, reconciliation and default provisions.
- Reconcile every remittance already collected.
- Ask for a written merchant cash advance payoff quote as of a specific date.
- Ask separately whether a discounted MCA payoff is available.
- Confirm how pending ACH withdrawals or processor splits will be credited.
- Ask whether the proposed amount constitutes full satisfaction.
- Confirm whether any other contractual amounts remain.
- Ask what happens to any UCC filing or guarantee.
- Verify wire instructions through a trusted contact channel.
- Preserve the quote, payment confirmation and post-payoff documentation.
A neutral request can read:
Please provide the amount required to satisfy our agreement in full as of October 5, 2026. If a contractual early-payment discount or negotiated merchant cash advance lump-sum payoff is available, please identify the amount and the deadline for receipt. Please also confirm how pending remittances will be credited and what satisfaction, UCC and guarantee documentation will follow cleared payment.
Do not wire a large payoff based solely on a verbal promise.
What Must Be in a Written Payoff Agreement?
A written merchant cash advance payoff quote or negotiated payoff document should make the economics understandable without requiring the merchant to reconstruct the conversation later.
Check for:
- exact legal name of the merchant;
- funder name;
- agreement date or identifying reference;
- payoff amount;
- good-through date;
- payment instructions;
- credit for remittances already collected;
- treatment of pending ACH or processor-split payments;
- treatment of applicable contractual fees;
- confirmation of whether the stated payment constitutes full satisfaction;
- procedure for any overpayment;
- UCC filing treatment;
- guarantee treatment; and
- timing for satisfaction or release documentation.
For a negotiated discounted MCA payoff, the most important issue is not merely the discounted dollar amount. It is whether the writing clearly says what happens after that amount clears.
MCA Renewal vs. Early Payoff: These Are Different Transactions
An MCA early payoff discount reduces or satisfies an existing position. A renewal ordinarily involves a new financing transaction and therefore should not be treated as equivalent to paying the old MCA off with the merchant’s own cash.
| Question | Early Payoff | Renewal |
| Existing position | Satisfied if payoff terms are met | Usually satisfied or netted from replacement transaction |
| New financing obligation | No, from payoff itself | Yes |
| New money to merchant | No | Usually |
| Main objective | Exit existing transaction | Obtain additional funding |
| Key figure | Final payoff | Net new usable proceeds |
| Main risk to compare | Liquidity used for payoff | New contractual obligation |
New York’s Financial Services Law expressly recognizes the importance of this distinction. For covered same-provider renewal financing, §808 requires disclosure of the amount used to pay certain unpaid finance charges or fees and the amount by which new disbursement is reduced to pay the prior outstanding balance. The statute even identifies the relevant disclosure concept as potential “double dipping.”
If the merchant plans to fund the payoff with another financing product, compare the existing payoff with the amount, cost, term, and usable proceeds of the replacement financing; the analysis is different from simply paying the MCA from available cash.
The practical considerations behind refinancing short-term debt with longer-term funding are especially relevant when the new transaction is being used to retire an existing short-term position.
For covered same-provider renewals in New York, Financial Services Law §808 also requires disclosures addressing the amount of new financing used to pay certain existing finance charges or fees and the reduction in new disbursement used to pay the prior balance.
That is why the merchant should compare net new usable cash, not just the headline amount of the renewal.
Why a Renewal Can Look Like a Payoff but Is Not One
Assume:
- current MCA payoff: $55,000;
- new transaction Purchase Price: $80,000.
If $55,000 of the new funding is applied to the existing position:
$80,000 − $55,000 = $25,000
The merchant receives only $25,000 before any other applicable deductions.
The old position may be closed, but a new obligation now exists.
That is fundamentally different from an MCA early payoff discount. The merchant should compare the new obligation created with the net new cash actually received.
A renewal should never be described as pay off MCA early savings simply because proceeds from the new transaction were used to extinguish the old one.
The Correct Order for Paying Off an MCA Early
Before acting on an MCA early payoff discount, follow the transaction in this order:
- Obtain the signed agreement and all addenda.
- Confirm the original Purchased Amount.
- Reconcile remittances through the current date.
- Identify every early-payment provision.
- Check eligibility conditions.
- Request a written payoff quote.
- Confirm the good-through date.
- Confirm whether the discount requires funds to be received—not merely initiated—by the deadline.
- Verify wire instructions independently.
- Send the payoff.
- Retain proof of payment.
- Confirm funds have cleared.
- Obtain written satisfaction.
- Stop or reconcile residual ACH and processor deductions.
- Address UCC termination after MCA payoff where a filing exists.
- Obtain confirmation concerning any MCA guarantee release.
This order helps avoid one of the most preventable payoff errors: wiring an estimated portal balance and discovering later that the funder calculated the final satisfaction amount differently.
Do Not Confuse a Portal Balance With a Payoff Quote
A portal can be useful for servicing, but it may not tell the merchant whether:
- an early-payment discount is active;
- the discount expires that day;
- pending ACH payments have posted;
- remittances in transit are included;
- additional contractual amounts remain;
- the displayed amount constitutes full satisfaction; or
- a payoff will stop future collection instructions.
For those questions, obtain a written merchant cash advance payoff quote with a specific good-through date.
This is especially important when a merchant cash advance prepayment discount expires quickly. A difference of one business day can matter if the contract ties the lower Purchased Amount to actual receipt of funds.
UCC Termination After MCA Payoff
Not every MCA has a UCC filing. Where a financing statement does exist, however, UCC termination after MCA payoff should be treated as a separate post-closing task.
If a UCC financing statement was filed in connection with the transaction, payoff and termination of the public filing should be treated as separate steps. Under New York UCC §9-513, termination requirements depend on the circumstances described in the statute; the 20-day demand provision for non-consumer collateral applies only when its statutory conditions are satisfied.
For the filing mechanics, the New York Department of State’s UCC amendment instructions identify termination as an available UCC-3 amendment action. Merchants should therefore confirm both what the governing agreement requires after payoff and whether the filing record was actually updated.
The merchant should first identify:
- whether a UCC filing actually exists;
- the filing number;
- the secured party of record;
- the filing office;
- whether the payoff documents require termination; and
- whether the public record later shows termination.
Do not assume that sending a payoff wire automatically changes the public UCC record.
Does the funder have 20 days to terminate the UCC?
A 20-day UCC termination deadline should not be stated as a universal MCA rule. Under New York UCC §9-513(c), the 20-day period for collateral outside the consumer-goods rule begins after the secured party receives a signed debtor demand and only applies when one of the section’s specified conditions is satisfied. The applicable state law and facts of the particular filing should therefore be checked before relying on a deadline.
New York UCC §9-513(c), for example, provides that in cases outside the consumer-goods rule, a secured party must send or file a termination statement within 20 days after receiving a signed debtor demand if one of the statute’s stated conditions is satisfied.
Those conditions address circumstances such as there being no secured obligation and no commitment to extend value, certain sold accounts or chattel paper having been discharged, or an unauthorized initial filing.
That is not a universal rule that every MCA UCC filing automatically disappears 20 days after payment.
The correct rule depends on the filing, transaction, governing jurisdiction, contract and facts.
What Happens to the Personal Guarantee?
An MCA guarantee release also should not be assumed from the fact that a payment was wired.
Some MCA agreements contain no personal guarantee. Others contain a guarantee of performance, payment, contractual representations, covenants or some combination of obligations.
The June 2026 Avanza agreement provides a useful current example. Its Personal Guarantee of Performance states that the guarantor guarantees the merchant’s performance of representations, warranties and covenants and contains additional provisions addressing renewals and modifications. The agreement also states that certain obligations remain until the Purchased Amount and other obligations are paid in full.
That example should not be generalized to every MCA.
When a guarantee exists, ask for written documentation confirming what has been satisfied after the payoff. If the business needs clear evidence for a sale, refinance or dispute prevention, have counsel review the MCA guarantee release or satisfaction language rather than assuming the guarantee has vanished automatically.
When an MCA Early Payoff Discount May Still Be a Bad Cash-Flow Decision
An MCA early payoff discount can create real dollar savings and still be a poor operational decision if obtaining the discount drains the business’s liquidity.
Suppose the merchant has $100,000 of unrestricted operating cash and can complete a payoff for $90,000.
The fact that the payoff saves money does not answer whether leaving the company with $10,000 is prudent.
Compare:
- dollar savings from the discount;
- cash remaining after payoff;
- upcoming payroll;
- payroll-tax deposits;
- sales-tax obligations;
- rent;
- inventory purchases;
- equipment repairs;
- seasonal working-capital needs;
- emergency reserves;
- accounts-receivable timing; and
- cost of replacing the cash if the company needs financing again.
A merchant that saves $10,000 but immediately needs a new high-cost $75,000 financing transaction may have improved one contract while weakening its overall cash position.
The cash-flow test becomes even more important when revenue changes materially during the year. A business with predictable busy and slow periods should account for its seasonal working-capital and cash-flow requirements before using a large share of available cash for an early payoff, particularly when payroll, inventory, taxes, or other peak-season expenses are approaching.
Should You Pay the MCA Off Early?
| Factor | Early Payoff May Be More Attractive When | Keeping More Cash May Be More Attractive When |
| Contractual discount | Material discount is documented | No reduction is available |
| Cash after payoff | Healthy reserve remains | Working capital would be depleted |
| Payroll/taxes | Adequately funded | Major obligations are approaching |
| Business sale | Clean payoff is needed for closing | No immediate transaction requires payoff |
| Refinance | Existing position must be cleared | Replacement funding would be expensive |
| Discount deadline | Enough time exists to verify terms | Deadline would force a rushed wire |
| UCC/guarantee | Cleanup process is clear | Satisfaction terms remain unresolved |
The right question is not simply whether an MCA early payoff discount exists.
The better question is whether the verified savings justify the cash that must leave the business today.
FAQs
Do MCA funders give early payoff discounts?
Some agreements do. An MCA early payoff discount must come from the contract, an addendum or a separately negotiated written payoff. The 2025 Cedar agreement filed with the SEC is a current public example containing lower Purchased Amounts for payment within specified early windows.
Does paying off an MCA early automatically save money?
No. The ability to pay early and a merchant cash advance prepayment discount are different. A contract can allow early payment while still requiring the remaining Purchased Amount, as the June 2026 Avanza agreement demonstrates.
What is an MCA prepayment addendum?
An MCA prepayment addendum modifies the original transaction by stating how early payment will be calculated. It may create a lower Purchased Amount, define discount windows, impose eligibility requirements and state how prior remittances are credited.
An early payoff addendum MCA clause should always be read together with the original agreement and later amendments.
How are merchant cash advance prepayment discount tiers calculated?
There is no universal formula. Some contracts use fixed early-payoff amounts; others may use a reduced factor rate early payoff calculation. The 2025 SEC-filed Cedar agreement used separately stated 30-day and 60-day Purchased Amounts rather than a universal industry factor schedule.
Can I negotiate a payoff if my contract has no discount?
Yes, you can request a discounted MCA payoff, but the funder is not automatically required to accept one. If a funder accepts a merchant cash advance lump-sum payoff, obtain written confirmation that clearly identifies the amount, deadline and effect of successful payment.
Is an MCA renewal the same as paying the advance off?
No. MCA renewal vs early payoff compares a new financing transaction with the retirement of an existing transaction. A renewal can use part of the new proceeds to satisfy the old position, leaving the merchant with less net new cash than the headline funding amount. New York Financial Services Law §808 expressly requires certain same-provider renewal disclosures addressing that reduction.
What happens to the UCC filing after payoff?
If a filing exists, confirm the applicable UCC termination after MCA payoff procedure. A UCC-3 can be used for termination, but the governing legal and contractual requirements vary. Do not assume the public filing disappears merely because the funder received the wire.
Should I pay off my MCA early if it uses most of my available cash?
Not automatically. Calculate the real pay off MCA early savings, then compare those savings with the liquidity remaining for payroll, taxes, rent, inventory and unexpected expenses. A large contractual discount may justify payoff when reserves remain strong. A small discount may be much less attractive if the business would need to borrow again immediately.
How to Evaluate an MCA Early Payoff Discount Before Sending Funds
The safest way to evaluate an MCA early payoff discount is to start with the executed agreement rather than the portal balance or a salesperson’s description.
Determine the original Purchase Price and Purchased Amount. Find every prepayment clause and early payoff addendum MCA provision. Reconcile remittances already collected. Then identify whether the agreement actually changes the Purchased Amount when payment occurs early.
Next, calculate the dollar savings—not just the percentage or factor. Obtain a written payoff good through a specific date and confirm that the amount constitutes the intended full satisfaction.
After payment, finish the cleanup. Confirm residual withdrawals have stopped, investigate UCC termination after MCA payoff if a filing exists, and document any required MCA guarantee release or satisfaction.
Finally, compare the savings with the operating cash being sacrificed.
A legitimate early-payoff reduction can be valuable. But the strongest decision combines three things: a verified contractual discount, a documented exit process and enough remaining liquidity to operate the business safely.